Company Snapshot
Company: China Automotive Systems, Inc. (China / Consumer Discretionary / Automobile Components)
Price (Nov. 15, 2024): US$4.47
Target price (12m): US$7
Expected share-price return: 56%
Investment risk: High
China Automotive Systems, Inc. (NASDAQ: CAAS) is a China-based manufacturer of power steering systems and components, serving domestic and global automakers with growing exposure to electric power steering (EPS) for electric and hybrid vehicles. The company operates through multiple subsidiaries and joint ventures in China and supplies both domestic automakers and multinational OEMs operating in the Chinese market.
Investment Thesis
The thesis rests on continued EPS growth and the recent stock repurchase program. CAAS presents a case study in a profitable, growing auto-parts supplier sector with a modest valuation relative to its earnings growth, cash generation, and expanding position in electric power steering (EPS) — a structurally growing segment tied to global vehicle electrification. The company has posted accelerating revenue, margin expansion, and triple-digit net income growth in the first half of fiscal 2026, alongside a debt-light balance sheet and an active share repurchase program. The board has authorized a $5 million share repurchase program, with purchases capped at prices no higher than $5.50 per share, effective through November 10, 2027.
Industry Backdrop and the EPS Opportunity
Global vehicle electrification is driving a structural shift from hydraulic to electric power steering systems, which are more energy-efficient and better suited to electric and hybrid drivetrains. CAAS has positioned EPS as a growth priority, with the segment now representing a meaningful and rising share of revenue—EPS products accounted for 46.8% of first-half 2026 revenue. Preliminary EPS unit sales trends point to continued momentum: Q3 EPS unit sales of 567,314 units (+40.1% year over year) and nine-month EPS unit sales of 1.46 million units (+32.7% year over year).
Financials, Liquidity, and Cash Flow
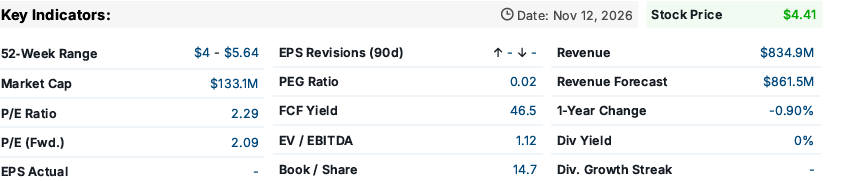
Management has set a 2026 full-year revenue target of $850 million, implying continued growth in the back half of the fiscal year. Taken together, the FY2025 and first-half 2026 results show accelerating top-line growth paired with disproportionate gross profit and net income growth — a pattern consistent with operating leverage as EPS mix rises and fixed costs are absorbed over a larger revenue base.
Year-end liquidity (cash and equivalent items) of approximately $256.7 million. No outstanding interest-rate-sensitive indebtedness as of December 31, 2025, limiting exposure to rising rates. Operating cash flow of $111.6 million in FY2025 comfortably exceeded capital expenditures of $37.2 million. This combination of a net cash balance sheet, strong operating cash flow relative to capex, and a disciplined, price-capped buyback authorization suggests a conservative approach to capital allocation. EPS growth (up from $1.42 in FY2025 to a $0.97 first-half 2026 pace) seems sustainable. Management’s willingness to repurchase shares at prices no higher than $5.50 provides a useful anchor for assessing intrinsic value.
Valuation Framework
From a valuation perspective, CAAS trades at a strikingly low forward P/E of ~2.1x for FY’26 and 1.75x for FY’27, with a price/book of ~0.30x and EV/EBITDA of ~1.1x. A $5 million share repurchase program was approved in November ’26. My 12-month price target of $7 is based on a 12-month target P/BV of 0.4x.
Catalysts
- Execution of the share repurchase authorization, which could support per-share metrics.
- Continued EPS mix shift driving further gross margin expansion.
- Achievement of, or progress toward, the $850 million 2026 revenue target.
- New or expanded OEM customer relationships that reduce concentration risk over time.
Risks
- Customer concentration: the top five customers accounted for 55.3% of 2025 sales, with Stellantis at 21.6% and BYD at 16.2% — meaningful dependence on a small number of relationships.
- Automotive industry cyclicality, which can pressure volumes and pricing during downturns in vehicle production.
- Pricing pressure from OEM customers, a persistent feature of the auto supply chain that can compress margins over time.
- China/U.S. geopolitical and regulatory risk, including tariffs, export controls, and evolving cross-border listing or disclosure requirements for China-based issuers.
- Small-cap liquidity risk, including wider bid-ask spreads and potentially higher share price volatility relative to larger, more heavily traded peers.
Thesis-Breakers
The following developments would materially undermine the investment thesis and warrant reassessment:
- Loss of, or material volume reduction from, Stellantis or BYD given their combined 37.8% share of 2025 sales.
- A reversal of gross margin expansion, suggesting EPS mix gains are not translating into durable profitability.
- A significant shortfall versus the $850 million 2026 revenue target without a credible explanation tied to temporary factors.
- New adverse regulatory, tariff, or delisting-related actions specifically affecting China-based U.S.-listed issuers.
- Suspension or substantial downsizing of the share repurchase program, which could signal reduced management confidence.
Conclusion
CAAS’s FY2025 and first-half 2026 results depict a company executing well on its EPS growth strategy, with margin expansion, accelerating net income growth, and a net-cash balance sheet supporting a modest capital return program. Preliminary third-quarter unit data suggest the growth trend has continued into the second half, though these figures remain incomplete relative to full financial statements. Customer concentration, auto-cyclical dynamics, and China-specific geopolitical and currency risks remain the primary considerations for anyone evaluating the name further. As always, this is an educational overview, not a recommendation, and readers should perform independent due diligence before drawing investment conclusions.
Sources and Disclosure
- SEC FY2025 Form 20-F
- SEC FY2025 Earnings Release
- SEC First-Half 2026 Release
- SEC November 2026 Preliminary Update
- China Automotive Systems Investor Relations
Disclaimer
This article is for educational and informational purposes only and does not constitute personalized investment advice, a recommendation, or a solicitation to buy or sell any security. Readers should conduct their own due diligence and consult a licensed financial advisor before making investment decisions. All figures are drawn from publicly filed company disclosures as cited below and are accurate as of November 15, 2026. The author holds a position in CAAS and has not been compensated for this analysis. This article does not constitute investment advice.

